About the area of activity

Public Audit - logo
The National Audit Office carry out public audits in implementing the tasks entrusted to it.

Public audit is an independent and objective assessment carried out by the Supreme Audit Institution in audited entities.

The National Audit Office carry out three types of public audit:

  • Financial audit – where the National Audit Office assess the data in the audited entity's annual (consolidated) financial statements and budget execution reports and issues an independent auditor‘s opinion.
  • Performance audit – where the activities of the audited entity are assessed in terms of economy, efficiency and effectiveness.
  • Compliance audit – where it assesses the compliance of the audited entity's activities with legal and/or other requirements and may express an independent auditor's opinion.

In order to improve the performance of the audited entity(ies) and to increase the benefits to society, the results of the public audits are used to formulate proposals - recommendations to address problems identified during the audit. Public audits are an important factor in promoting the efficiency, accountability and effectiveness of public sector institutions and improving the lives of citizens.
   

DOCUMENTS PROVIDING GUIDANCE TO PUBLIC AUDITING

Professional standards and guidelines are essential to ensure the reliability, quality and professionalism of public sector audit. The National Audit Office carry out audits in accordance with the INTOSAI Framework of Professional Pronouncements consisting of the INTOSAI Principles (INTOSAI-P), the International Standards of Supreme Audit Institutions (ISSAIs) and Guidelines (GUID). Financial audits are also guided by the International Standards on Auditing (ISAs) issued by the International Auditing and Assurance Standards Board of the International Federation of Accountants, which are incorporated into INTOSAI's Standards on Financial Auditing (ISSAIs 2000-2899).

In accordance with the requirements of the ISSAIs, ISAs (in the case of financial audits) and INTOSAI Guidelines, the National Audit Office has developed manuals on Financial, Performance, Compliance and Information Technology audits. The Information Technology Audit Manual also takes into account the Information Systems Audit Standards and Guidelines of the International Information Systems Audit and Control Association (ISACA), as well as other ISACA methodological material. The objective of the audit guidance documents prepared by the National Audit Office is to provide and explain the general and procedural requirements for audits in order to ensure the audit quality.

 
AUDITOR’S RESPONSIBILITY IN PERFORMING FINANCIAL AUDIT

Illustration: Auditor’s responsibility for financial audits

By conducting audits in accordance with International Standards on Auditing and International Standards of Supreme Audit Institutions, we use professional judgement and professional scepticism throughout the audit. We also:

  • Identify and assess the risks of material misstatement of the (consolidated) financial and budget implementation accounts, whether due to fraud or error, design and perform procedures in response to those risks, and obtain sufficient appropriate audit evidence to provide a basis for our opinion. Detection risk of a material misstatement due to fraud is greater than detection risk of a material misstatement due to error, as fraud may include deception, forgery, intentional omission, misinterpretation, or override of internal controls;
  • assess the internal control of the entities/group of entities involved in an audit to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the entity's/group of entities' internal control;
  • assess the appropriateness of accounting policies used and the reasonableness of accounting estimates and related management disclosures;
  • assess the overall presentation, structure and content, including disclosures, of the (consolidated) financial statements and the budget implementation reports and whether they present the underlying transactions and events in a manner that is consistent with the concept of fair presentation.

As part of our group audit, we also obtain sufficient appropriate audit evidence about the financial information or activities of the entities within the group to enable us to express an opinion on the group's consolidated financial statements and budget implementation reports. We are responsible for directing, supervising and performing the group audit. We are solely responsible for expressing our opinion on the audit.

We communicate to those charged with governance, among other things, the scope and timing of the audit and significant audit observations, including significant deficiencies in internal control that we identify in the course of the audit.

Among the matters that we communicate to those charged with governance, we highlight those that were the most significant in the financial audit for the current period and are considered to be key audit matters. We describe such matters in the report if we are not prohibited by law or regulation from disclosing the matter publicly or if, in very limited circumstances, we determine that the matter should not be disclosed because the adverse consequences of disclosure might reasonably be expected to outweigh the benefits to the public.

PLANNING OF PUBLIC AUDIT

Illustration: Planning of public audit

In order to implement the tasks assigned to it, the National Audit Office determine each year the scope of activities in the Annual Activity Plan.

The Institution is independent in deciding which audits or assessments are carried out, and only the Seimas, by its resolution, may assign the National Audit Office to carry out public audit within the scope of its competence.

The institution’s Annual Activity Plan is drawn up in such a way to cover the most important areas of public sector activities and to carryout all public audits and assessments assigned to the National Audit Office by laws and other legal acts. The Annual Activity Plan is approved by the Auditor General after it has been presented to the Seimas Committee on Audit.

 
PUBLIC AUDIT RECOMMENDATIONS

Illustration: Public audit recommendations

In order to maximise the impact of public audits and positive developments in the public sector, public audit recommendations are provided during each audit. Taking into account the extent of changes for the implementation of goals of state policy, public governance and society, they are marked as high, medium and low importance. Recommendations are the possibility of the National Audit Office as the supreme audit institution to initiate processes of improvement of the activities of public sector institutions, increase the value of the public sector to society and benefit to the State.

For the implementation of the recommendations and for monitoring their implementation, each time a plan of implementation of recommendations is being prepared and coordinated with the audited entity, which is part of the public audit report. The plan specifies the changes sought by the implementation of the recommendations, their evaluation indicators and values, the deadlines for the implementation of the recommendations and the measures proposed by the audited entity implementing the recommendations, and other important information. The audited entity informs the National Audit Office of the results of the implementation of the recommendations within the deadlines agreed in the plan of implementation of recommendations.

In order to strengthen the impact of the audit on public finance management and control systems and on the improvement of public administration in audited areas, the National Audit Office carries out regular monitoring of the implementation of recommendations. The results of this monitoring: the status of implementation of the recommendations, the responsible entities and the changes that have taken place following the implementation of the recommendations can be followed in Lithuanian in continuously updated open data on the institution’s website. Twice a year, before the spring and autumn sessions of the Seimas of the Republic of Lithuania, the National Audit Office submits reports on the monitoring of the implementation of the recommendations to the Seimas Committee on Audit. The reports review the status of implementation of the audit recommendations of high importance for the past half-year, draw attention to the problems observed when implementing the recommendations, identify a list of laws necessary to implement the recommendations and achieve the impact of the audit. These reports are available on the website of the National Audit Office.

 
COOPERATION

Cooperation icon

When implementing its functions, the National Audit Office cooperates with many institutions, including the Office of the President, Seimas, Government, the Association of Municipal Controllers as well as directly with public sector institutions as present or former audited entities. Cooperation of the National Audit Office with the Seimas is very important in making a positive and effective impact of public audit on public finance and asset management and control system. When exercising parliamentary scrutiny of the executive, the Seimas uses the results of the public audit as one of the parts of the system of parliamentary scrutiny and seek that the entities in which the National Audit Office has carried out public audit implement public audit recommendations. The National Audit Office cooperates most intensively with the Seimas Committee on Audit, which regularly considers public audit reports. Depending on the area audited, audit reports (as well as other products produced in implementing other functions of the institution) are submitted for consideration to other committees and commissions of the Seimas.

To implement advanced methods of budgetary governance and internal control in the public sector close cooperation is maintained with the Ministry of Finance, the Association of Internal Auditors, the Association of Municipal Controllers, municipal control and audit services, the Lithuanian Chamber of Auditors in improving the audit and accounting legislation, public sector audit methodologies, and sharing experience.

The National Audit Office has concluded cooperation agreements with the Bank of Lithuania, the Chief Official Ethics Commission, the Prosecutor General’s Office, the Public Procurement Office, the Special Investigation Service, the Financial Crime Investigation Service, the State Tax Inspectorate, the Competition Council, the Ministry of Finance, the Ministry of Social Security and Labour, the Faculty of Economics and Business Administration of Vilnius University, Vytautas Magnus University, Mykolas Romeris University, Lithuanian Chamber of Auditors, the Association of Municipal Controllers, the Association of Internal Auditors.

The National Audit Office also co-operates with various institutions when submitting conclusions, comments and proposals concerning drafts of laws and other legal acts, considers and prepares conclusions regarding draft decisions of the Government.

The National Audit Office maintains collegiate relations with the academic community: representatives of the institution are regularly invited to give lectures to students of higher education institutions, students of general education schools come to get acquainted with the activities of the institution.

The Institution also invites the general public to cooperate; when annually drawing up a public audit programme and deciding which audit topics to choose, the National Audit Office addresses the public by proposing to contribute to the development of the public audit programme in a specially designed tool for this purpose on the website where it is possible to indicate noticeable public sector failures that the National Audit Office could assess during the audit. Proposals of citizens are evaluated and taken into account when choosing directions and topics of public audit.

The National Audit Office also liaise with its peers in foreign countries – other supreme audit institutions. One of the most important expressions of this cooperation is the cooperative international audit. National Audit Office is an active member of the International Organisation of Supreme Audit Institutions INTOSAI and the European Organisation of Supreme Audit Institutions EUROSAI, participates in the work of committees and working groups of these international organisations. Read more about this cooperation in the section Internationality.

Read more

News

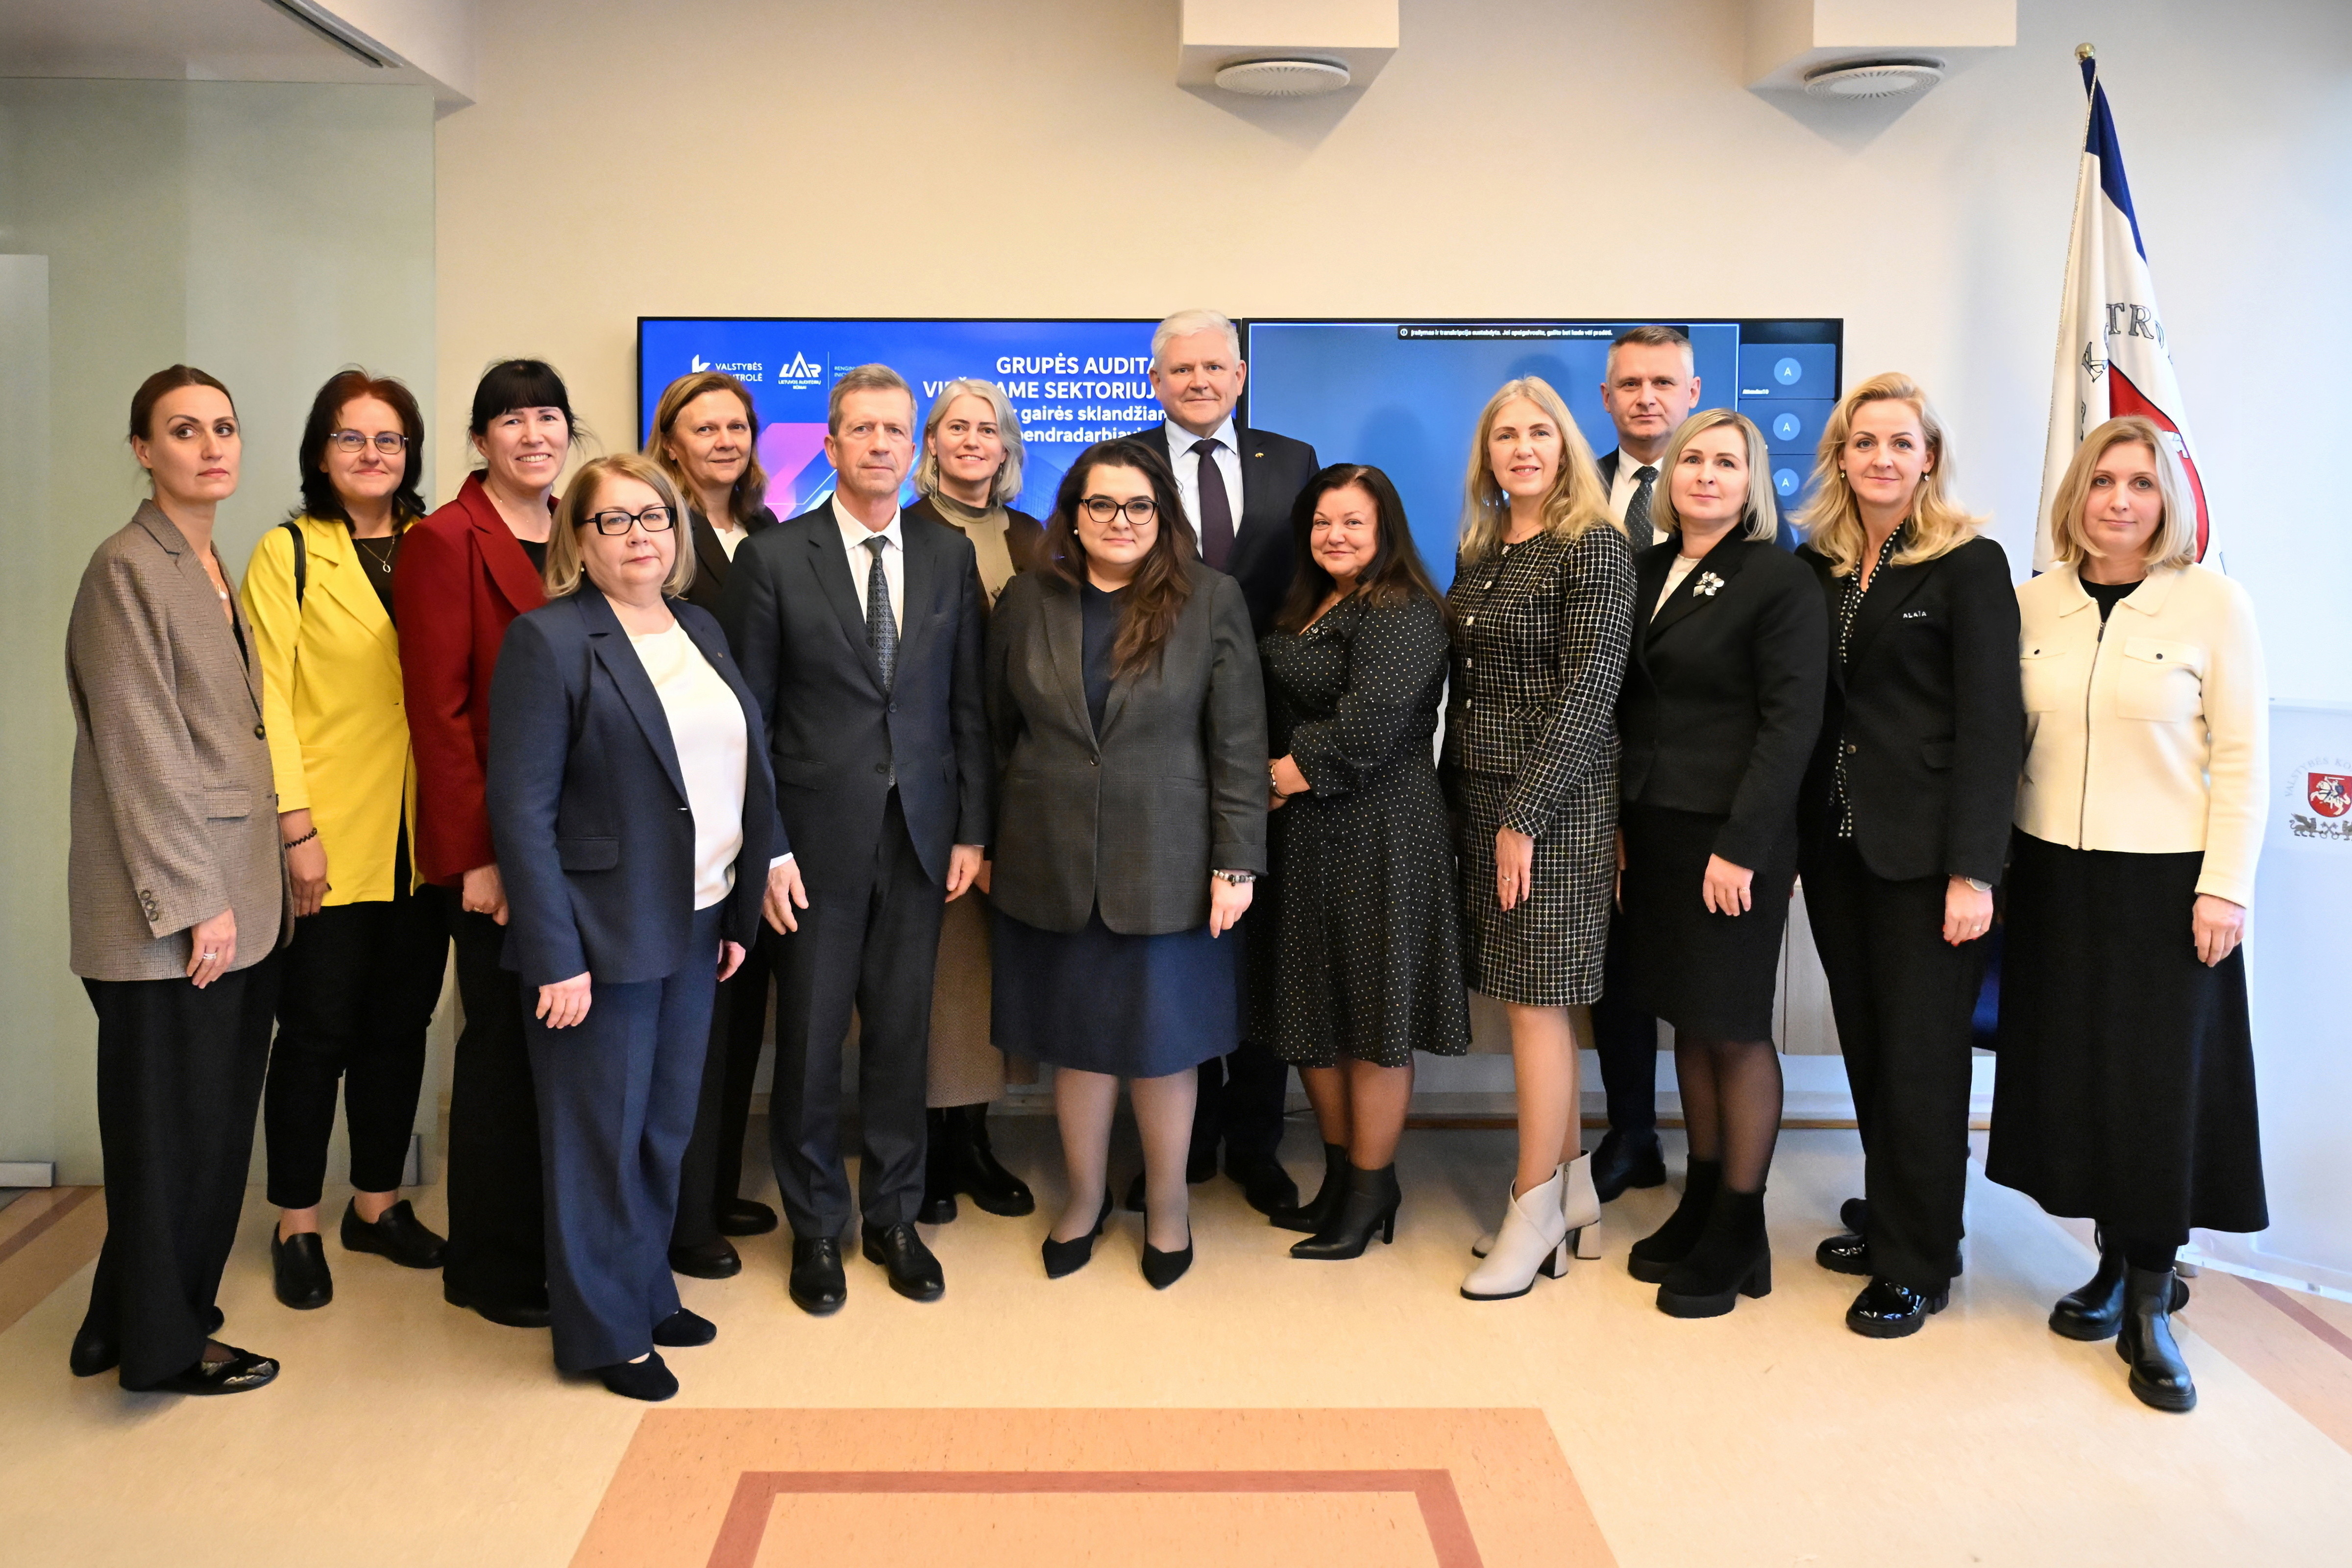
Picture for National Audit Office presented guidelines for reliable audit of the 2026 state financial accountsAt a conference held at the National Audit Office (NAO) on 12 November “Group Audit in the Public Sector: Changes and Guidelines for Smooth Cooperation”, the auditing community, representatives of the Ministry of Finance and municipalities discussed key changes to public sector reporting and audit regulation for 2026.
  
The National Set of Annual Accounts covers more than 3,100 public sector entities and state and municipal administration bodies, whose assets, according to the results of the financial audit of the 2025 National Set of Annual Accounts carried out by the National Audit Office, exceed EUR 90 billion, while their liabilities amount to nearly EUR 40 billion.
  
At the event, organised by the National Audit Office in cooperation with the Lithuanian Chamber of Auditors (LAR), it was emphasised that, in order to ensure the reliability of these data as a whole, more transparent management of public resources and higher audit quality, smooth cooperation between all parties involved in the audit process and the timely exchange of information necessary for the audits are of paramount importance.
  
“When deciding what the state can afford, we need to know with certainty what assets we hold and what liabilities we have already incurred. When preparing the 2026 accounts, data on state and municipality owned enterprises classified as part of the public sector will be included for the first time. The public will see a more detailed picture of the state’s finances. It is our duty, as auditors, to independently assess whether this picture can be trusted,” says Auditor General Irena Segalovičienė.

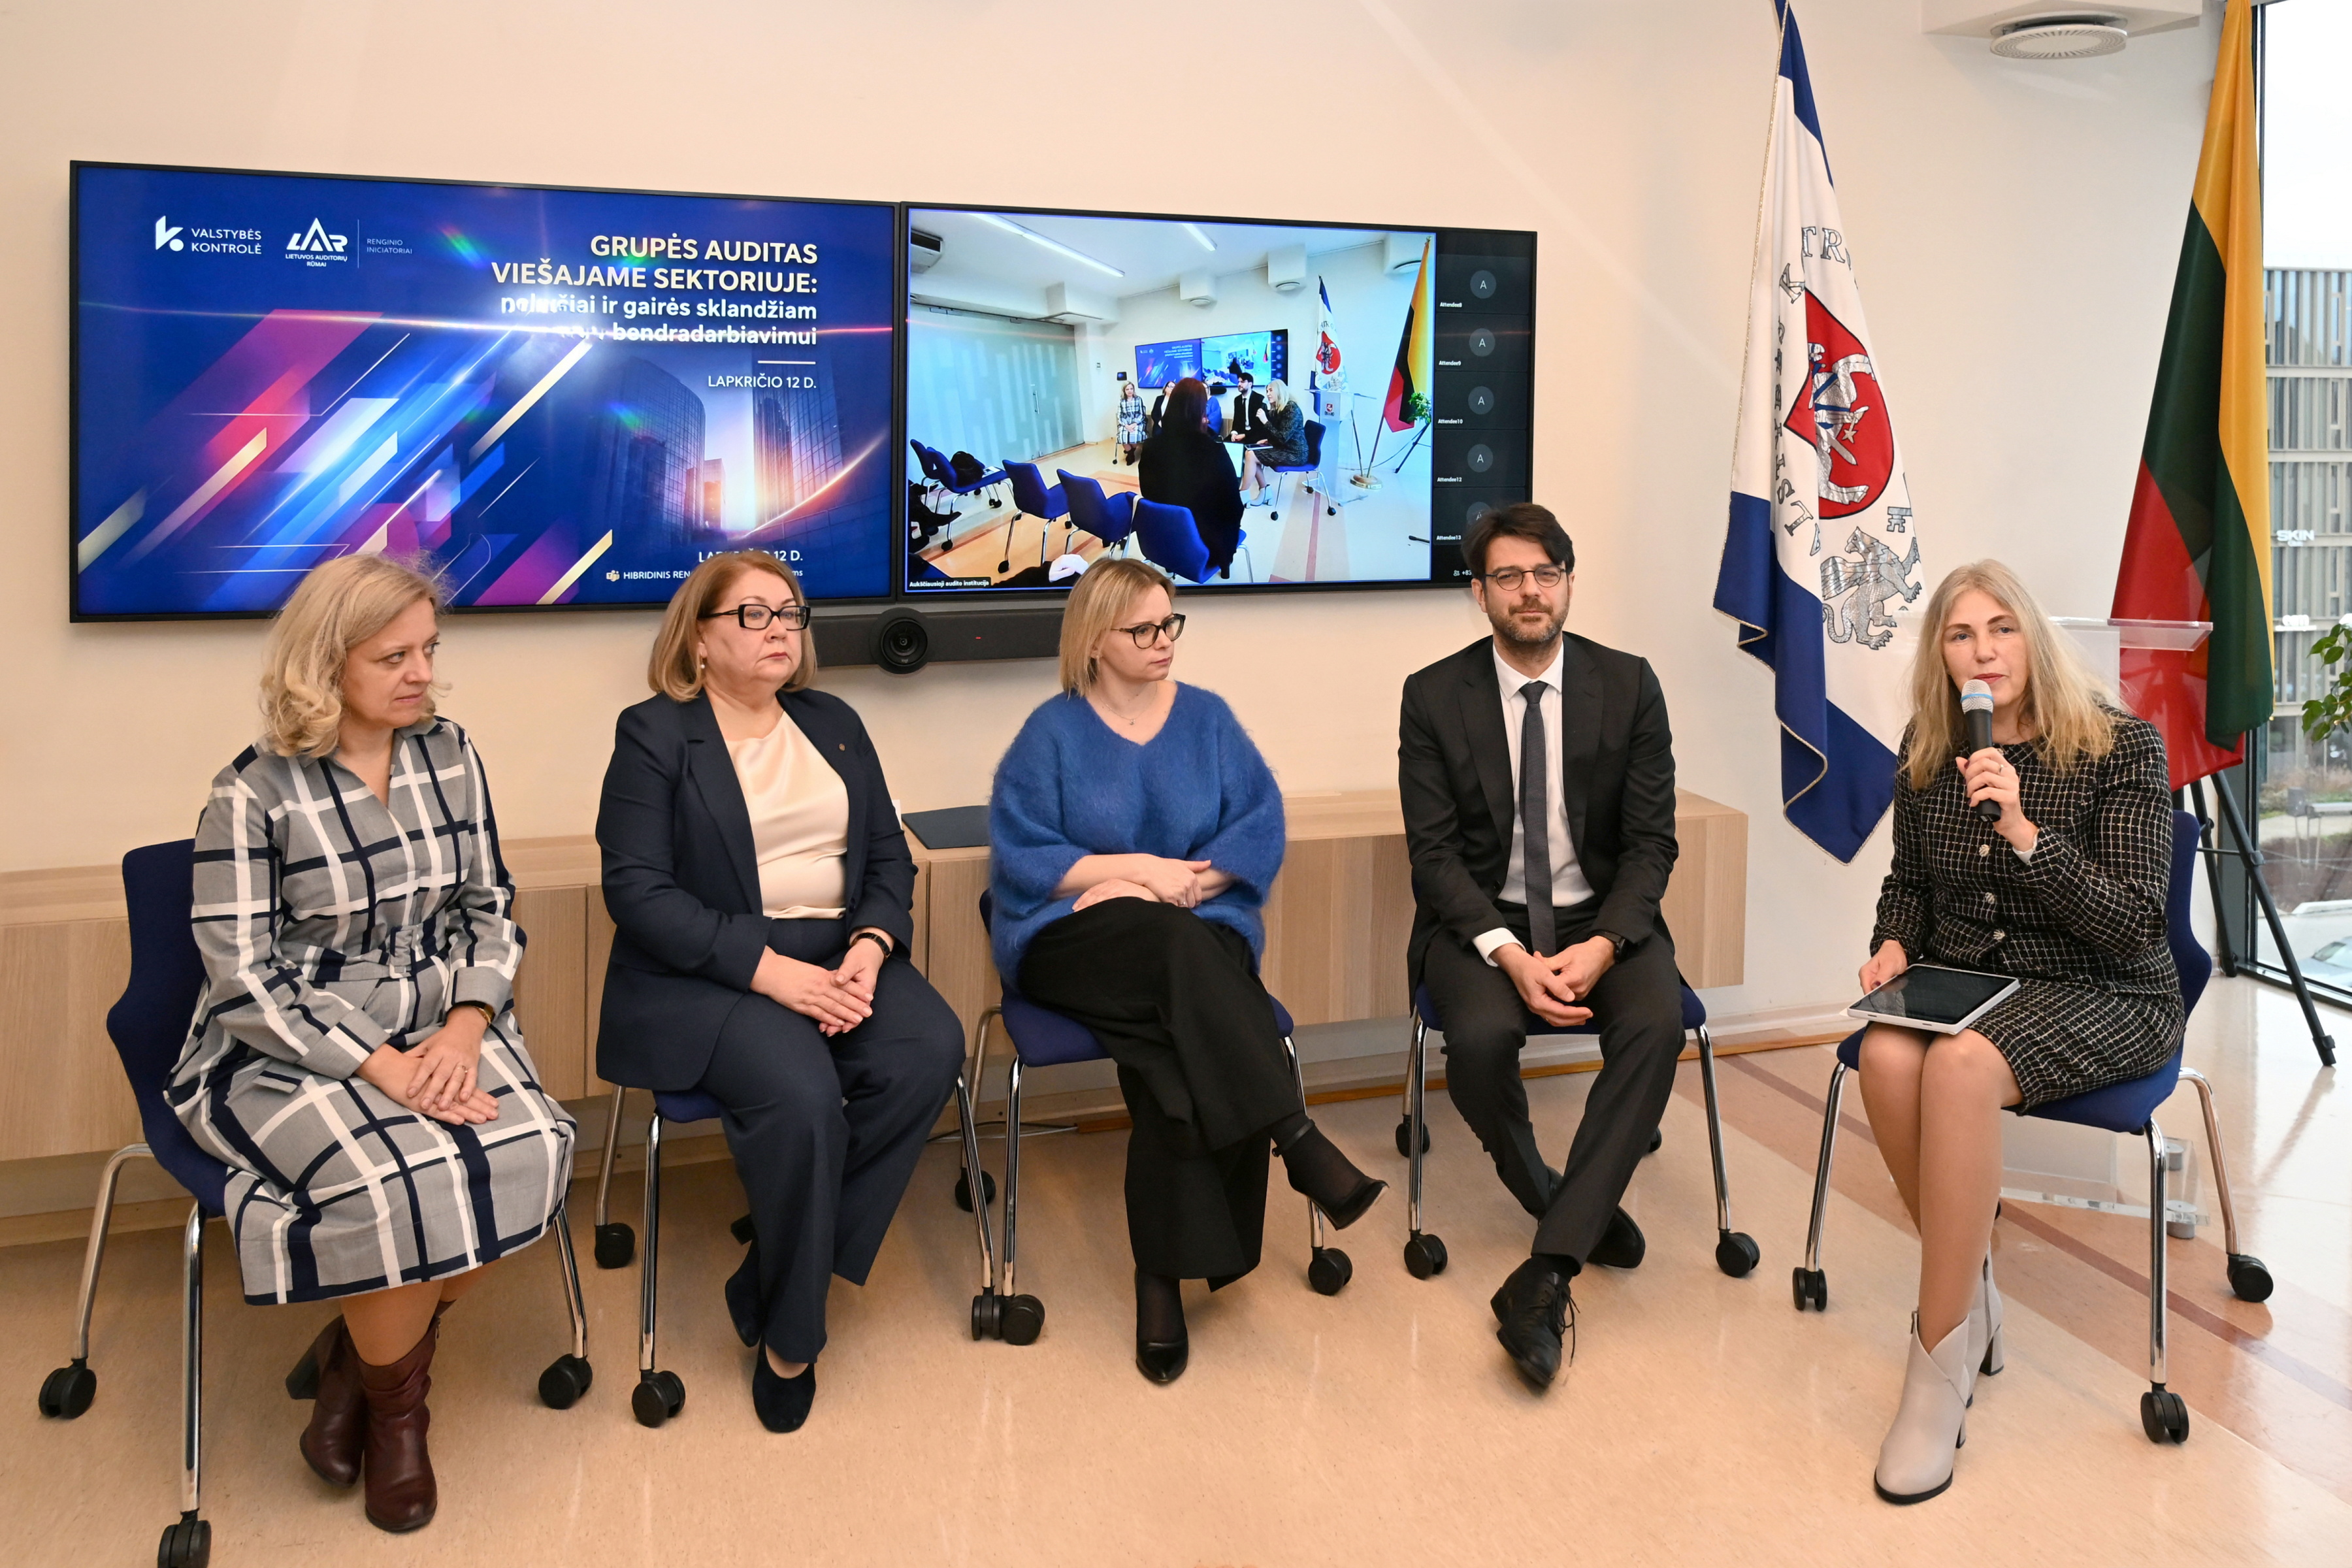
Picture for National Audit Office presented guidelines for reliable audit of the 2026 state financial accountsOne of the key issues discussed at the conference was the changes to public sector financial reporting due to come into force in 2026 and their practical implementation. During the event, Ingrida Muckutė, Director of the Department of Reporting, Audit, Property Valuation and Insolvency Policy at the Ministry of Finance, reviewed the legal framework and the obligations of entities to provide data, identified the main challenges arising from the changes, and offered practical advice on the transition to the new requirements.
  
The conference placed particular emphasis on the group audit process and smooth cooperation between the group auditor and the component auditors. Danguolė Krištopavičienė, Head of the Financial Audit Department 1, and Lina Venckūnaitė, a methodologist from the Innovation and Methodology Department at the National Audit Office, presented the methodological requirements for financial audits of the National Set of Accounts and the State Set of Accounts, discussed the audit process, guidelines for cooperation with component auditors, and the challenges that have emerged in the course of previous audits.
 
Simonas Rimašauskas, a partner at Deloitte Lithuania and representative of the Lithuanian Chamber of Auditors, shared his insights on how companies can prepare effectively for the audit process and on its key practical aspects.
  
In the discussion that concluded the conference, participants addressed specific issues arising from the application of the new requirements, shared their experiences and sought solutions to strengthen cooperation between the various parties involved in the audit process.
  
The dialogue initiated by the NAO and the LAR provided an opportunity for the various parties involved in the audit and reporting process to discuss in advance the forthcoming changes and the practical aspects of their implementation. This is an important step towards ensuring that public sector financial statements are not only properly prepared but also assured by an independent auditor’s opinion.

Picture for National Audit Office: Auditors from five countries focus on the progress and risks of Rail BalticaOn 29–30 October, representatives of the supreme audit institutions (SAIs) of Lithuania, Latvia, Estonia, Poland and Finland met to discuss the progress of the strategic Rail Baltica project, the main risks associated with its implementation, and the joint audit being carried out by Lithuania, Latvia and Estonia entitled “Implementation of the Rail Baltica Project”.
  
„“As Europe prepares to strengthen its defence capabilities by 2030, we must ask a fundamental question: will the infrastructure on which our security depends be ready when it is needed? The success of Rail Baltica cannot be measured solely by the progress made by individual countries. The three countries may successfully implement their respective sections of the project, but this does not necessarily mean that we will have a single operational railway. This is precisely why our joint audit must reveal not only national risks but also the interconnections between them, identify the obstacles hindering the implementation of the entire project, and help ensure that responsible decisions are taken in a timely manner,” says Auditor General Irena Segalovičienė.
  
Rail Baltica is one of the most important infrastructure projects in the Baltic region, which will integrate Lithuania, Latvia and Estonia into the European high-speed rail network, ensure faster movement of passengers and freight, encourage investment and reduce the Baltic states’ dependence on eastern transport corridors. The project is also of strategic importance for the region’s security and military mobility. Russia’s war against Ukraine has further highlighted the need to ensure the rapid and smooth movement of military equipment and other resources between countries. However, earlier this year, the European Court of Auditors noted that there is still no clear final deadline for the completion of the entire Rail Baltica project.
  
Joint audit focuses on the operation of the entire rail link
  
The SAIs of Lithuania, Latvia and Estonia, having previously carried out one cooperative audit (in 2019) and one joint review (in 2024) of the Rail Baltica project, are currently conducting a second joint audit of the project. The 2024 review revealed that an additional EUR 19 billion is required to fully implement the project. This funding requirement poses significant risks regarding the securing of project funding and adherence to implementation deadlines.
  
The joint audit currently underway is assessing whether the management of the project’s progress, public procurement and contracts is effective and adequate. The auditors are also analysing the implementation of recommendations from previous audits, as well as the measures aimed at mitigating the risks of a funding shortfall and project delays and assessing their adequacy.
  
A key benefit of the joint audit is the opportunity to examine the project not only from the perspective of individual countries, but also from the perspective of the entire international rail link. Even if one section of the railway is successfully completed, its benefits may remain limited if the installation of related infrastructure in another country is delayed or if the necessary decisions regarding future railway operations have not been taken.
  
It is therefore important to assess how the countries’ implementation timetables, funding arrangements and readiness for railway operations align with one another. A joint audit should help to identify systemic obstacles and provide recommendations that would contribute to tangible progress across the entire project.
  
Experience of the five countries and further cooperation
  
On the first day of the meeting, representatives of the SAIs of Lithuania, Latvia, Estonia, Poland and Finland will present the progress of the Rail Baltica project and the main risks in their respective countries, share their audit experience and discuss common challenges. During the meeting, the project implementers, LTG, will also present the technical aspects of Rail Baltica. Participants will also visit the project’s construction sites, where they will be able to familiarise themselves with the progress of the work being carried out.
  
On 30 October, members of the joint audit team from Lithuania, Latvia and Estonia, as well as members of its Coordination Group, will discuss the draft audit report currently being prepared, the analysis carried out by an independent expert, and the next steps in their joint work.
  
Given the strategic importance of this ambitious international project and the scale of the financial resources required for its implementation, the SAIs of Lithuania, Latvia and Estonia have been cooperating since 2016, when they signed a memorandum of understanding on project monitoring. Regular meetings of the Rail Baltica Project Monitoring Task Force have also been taking place since 2016, with representatives from the SAIs of Poland and Finland also participating.
  
Such cooperation enables not only the consistent monitoring of the project’s progress, but also the assessment of cross-border risks, the identification of systemic issues and the provision of evidence-based recommendations to decision-makers.

Picture for International audit: Rising life expectancy requires governments to change their approach to an ageing populationAs part of the international parallel audit “Preparedness of Governments for an Ageing Population”, nine countries [1] were assessed on how they are preparing for the challenges posed by an ageing population and whether they are ready to ensure the well-being of older people.
  
The well-being and quality of life of older people after retirement were examined in the international audit using the examples of Lithuania, Poland and Israel. Based on the results of national audits in these countries, a comparison was made of the opportunities available to older people to continue working after reaching retirement age and how governments are addressing the issue of loneliness. The situation in Lithuania was assessed in the findings of the public audit “Promoting Active Ageing”, carried out by the National Audit Office in the spring.
  
According to the findings of the international audit, life expectancy in the countries audited [2] is expected to increase by approximately 3–4 years by 2050, while the ratio of older people to the working-age population rose steadily in all countries between 2000 and 2024. These demographic trends are placing increasing pressure on healthcare, long-term care, pension and social security systems. In Lithuania, this challenge is also becoming increasingly pressing. According to National Audit Office’s audit findings, at the start of 2026, 28.8 percent of the country’s population were aged 60 and over, and by 2100 this proportion is forecast to rise to 43.5 percent.
  
“Increasing life expectancy is a tremendous achievement for society, but at the same time it raises a very specific question for the state: are we providing people with the opportunities not only to live longer, but also to remain active and independent for as long as possible, and to participate in society? Ageing policy cannot be limited to declarations or isolated measures. We need clear objectives, accountability and solutions that reach the individual: providing opportunities for those who wish to continue working, learn or participate in community life, while ensuring that those experiencing loneliness or in need of support receive the necessary services. I cannot imagine a demographic policy without a policy on ageing, which is why I urge that, while addressing the birth rate, we must not forget the strategy for active ageing,” emphasises Auditor General Irena Segalovičienė.
  
In Lithuania, the employment rate among older people is close to the OECD average, but there is a lack of specific employment targets
  
The opportunities for older people in Lithuania, Poland and Israel to continue working after retirement vary. In Lithuania in 2024, 13.2 percent of people aged 65 and over were in work – similar to the average for Organisation for Economic Co-operation and Development (OECD) countries (13.7 percent). Meanwhile, in Poland, the employment rate for this age group stood at 6.1 percent, and in Israel at 21.1 percent.
  
In Lithuania, it is possible to work while receiving a full old-age pension; however, neither Lithuania nor Poland has set specific targets for the employment of people of retirement age. Israel has set such targets – by 2030, it aims for 43.5 percent of men aged 67–74 and 28.5 percent of women in this age group to be in work. Nevertheless, the audit findings note that the measures in place in all three countries are insufficient, to significantly increase the opportunities for older people who are willing and able to work to continue their professional careers.
  
Israel is implementing the “Seniors at Work” programme, which aims to change the labour market’s attitude towards older workers and create more employment opportunities for them. The programme helps people aged 60 and over to look for work, provides them with the necessary skills and acts as an intermediary in finding suitable jobs. The country also operates a special programme for the employment of older people in the civil service.
  
The National Audit Office has set out the measures needed to increase the employment of people of retirement age who are willing and able to work, while combining work and a pension, in the recommendations of the public audit carried out in the spring. It was recommended that the Ministry of Social Security and Labour of the Republic of Lithuania remove age restrictions on working in the public sector, and take decisions on the introduction of flexible working arrangements, additional safeguards, health promotion or other support measures for older people, taking into account their identified needs; to plan and implement integrated measures to prepare pre-retirement-age individuals for retirement, which would help them make a smooth transition to a new stage of life in retirement and remain active in society and/or the labour market; as well as setting out the target employment rate for people of retirement age in strategic planning documents and monitoring changes in this rate.
  
Loneliness – a recognised problem, yet those experiencing it remain overlooked
  
Loneliness is another issue examined by auditors in Lithuania, Poland and Israel. Although different measures are in place in each country, the international audit revealed that all three countries lack effective ways of identifying lonely older people and ensuring they receive the support they need.
  
A survey conducted as part of the National Audit Office’s audit showed that 34.5 percent of older respondents had felt lonely very often, often or sometimes over the past year. As many as 87 percent of those surveyed who had experienced loneliness did not seek help, whilst 52 percent did not take part in activities that could help reduce their feelings of loneliness.
  
In Lithuania, loneliness is not identified in strategic documents as a distinct social policy issue; there is a lack of indicators to measure it, and no institution is responsible for the systematic identification of lonely older people. A similar situation is observed elsewhere: in Poland, loneliness is not measured by official indicators, while in Israel, although the indicator is measured, only 18 percent of lonely older people are identified. This shows that simply recognising the problem and monitoring its scale is not enough to ensure that support reaches those who need it; solutions are therefore essential.
  
The map of well-being indicators for older people being introduced in Israel is one example of how we might contribute to tackling the problem of loneliness among older people. With a view to achieving a breakthrough in this area, the National Audit Office recommended to the Ministry of Social Affairs and Labour as early as this spring that it assess the impact of loneliness on people’s mental and physical health, their quality of life and the state’s social and healthcare systems; set a target for the prevention and reduction of loneliness; an indicator of the level of loneliness amongst older people and a target value for it, establish assessment criteria for identifying lonely individuals, plan measures to reduce loneliness, and devise measures to encourage lonely people to seek help.
  
Direction is already set, but what matters most is the impact of the measures
  
The general conclusions of the international audit reveal that it is important for states to move from declared policy directions to concrete, funding-based actions, clear responsibilities and measurable outcomes. This requires a long-term and cross-sectoral approach to public policy, so that increased life expectancy translates into better health, greater independence and more active participation in society.
  
In June 2026, Lithuania adopted the Framework Law on the Policy for Older People, which aims to strengthen the coordination of policy in this area and to define the responsibilities of institutions more clearly. However, the results of the international audit serve as a reminder that legal and strategic frameworks alone are not enough – real progress will depend on how the envisaged solutions are implemented and what tangible changes they bring about in the lives of older people.
  
In implementing the National Audit Office’s recommendations, the Ministry of Social Affairs and Labour, the Ministry of Health, and the Ministry of Education, Science and Sport have committed to implementing specific measures regarding employment, voluntary work, and access to social and health promotion services. It is important that these measures are implemented on time, as promised. Meanwhile, in the auditors’ view, the measures proposed by the Ministry of Culture are not geared towards practical changes aimed at increasing the participation of older people in cultural activities.


[1]  Nine supreme audit institutions took part in the international parallel audit „Preparedness of Governments for an Ageing Population“: those of Albania, Israel, Poland, Lithuania, Malta, North Macedonia, Paraguay, Portugal and Slovakia.
[2]  Albania, Israel, Poland, Lithuania, Malta, North Macedonia, Paraguay, Portugal, Slovakia.
   

International Parallel Audit on Preparedness of Governments for an Ageing Population